Chocolate Finance Opens UAE Accounts, Its Third Market After Singapore and Hong Kong
The firm pays 4.4% a year on the first AED 100,000 or US$25,000, with no minimum investment and no lock-in, using its own fund rather than third-party vehicles.
Nadia Mansour Nadia Mansour covers fintech across the UAE and MENA for Anecdoted -- digital banking, payments licences and the startups building around them. nadia@anecdoted.com
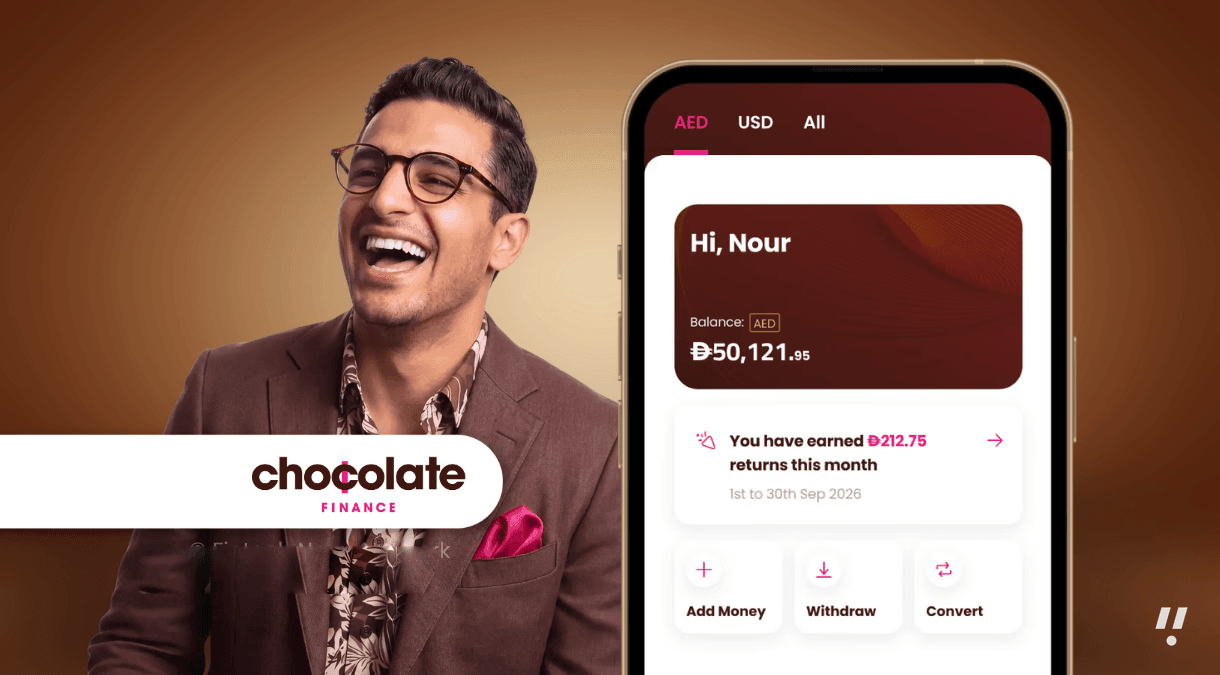
Chocolate Finance has opened for business in the UAE, taking the firm outside Singapore and Hong Kong for the first time. Accounts are available to UAE residents and to international non-residents, and customers can hold and invest in dirhams, US dollars, or both.
The headline rate is 4.4% per annum on the first AED 100,000 and on the first US$25,000. Balances above those levels can earn up to 4.4%, and a top-up programme applies to investments that sit within the thresholds. That programme carries terms and conditions. There is no minimum investment requirement and no lock-in period.
A different structure from Singapore and Hong Kong
Founder Walter de Oude said the UAE offering is built differently from the products the company runs in its two existing markets. Instead of routing customer money through third-party funds, the UAE business invests through the Chocolate Global Income Fund, a vehicle the company owns. De Oude said that arrangement brings down operating costs, and that the saving allows slightly higher returns to be passed to customers.
Chocolate Finance and its fund hold licences from the UAE Capital Market Authority and are regulated by it.
The company cautioned that invested capital is at risk, and that past performance does not indicate future returns.
Running its own fund rather than buying into outside ones changes what the firm controls. The cost of the wrapper, the choice of underlying holdings and the speed at which either can be adjusted all sit with Chocolate Finance rather than with an external manager, which is the basis for de Oude's claim on pricing. It also concentrates the operational burden: an in-house vehicle needs its own compliance, valuation and reporting, and the regulator's oversight lands on the fund as well as the distributor.
The no-lock-in, no-minimum terms put the account in the same conversation as an instant-access savings product, where a quoted rate is the main thing a customer compares. The difference is what backs it. A bank deposit carries a deposit guarantee in most markets; an investment in a fund does not, which is why the company's own risk warning matters more than the rate for anyone deciding where to park cash they might need quickly.
For Chocolate Finance, the UAE is a test of whether a model built in two Asian hubs travels. The Gulf's dirham is pegged to the dollar, so a customer holding either currency is taking little exchange risk between the two, and the population is heavily made up of expatriates who keep accounts across borders and often send money home. Those are the customers the offer appears designed for.

