Abu Dhabi's DeFa by InvoiceMate Ties Web3 Liquidity to SME Invoice Finance
The Abu Dhabi fintech converts B2B invoices into short-duration yield for institutional allocators while borrowers draw fiat without touching crypto.
Karim El-Sayed Karim El-Sayed covers company news, policy and regulation across the UAE and wider MENA for Anecdoted, with a focus on how new rules and licences reshape how startups operate. karim@anecdoted.com
DeFa by InvoiceMate is an Abu Dhabi fintech, founded in 2021, that describes itself as an AI-native PayFi platform. It aims at two structural problems in global trade at once: a financing shortfall the company sizes at US$5.2 trillion for micro, small and medium enterprises, and cross-border settlement routes that leave working capital stuck in transit for days.
The model links Web3 liquidity to real-world assets. B2B invoices and payment flows become the collateral behind short-duration yield products sold to institutional allocators. In practice, an unpaid invoice is converted into an instrument an institution can hold, while the business that issued it gets paid now rather than later.
Fiat in, crypto out of sight
Three components carry the product: autonomous AI underwriting, stablecoin settlement executed through smart contracts, and Virtual IBAN lockboxes. A business can draw fiat capital immediately and, according to the company, never has to touch cryptocurrency at any point in the process. That abstraction is the design goal. The borrower stays on ordinary banking rails while the settlement layer beneath runs on-chain.
Guarding against double-financing
Invoice finance has a long-standing weakness. The same receivable can be pledged to more than one lender, and the fraud is hard to spot after the fact. DeFa counters this with on-chain "Proof of Value" hashing, which leaves a record when a receivable has already been used. Underwriting runs through a risk engine the company calls "Know Your Receivable", or KYR. DeFa says it is the only full-stack PayFi bridge that combines these elements with complete fiat abstraction.
hashing, which leaves a record when a receivable has already been used. Underwriting runs through a risk engine the company calls
The company reports a default rate below 0.2%, a figure it describes as industry-leading, and says its liquidity routing operates under full compliance across both traditional finance and Web3 ecosystems, without the delays that normally come with moving money between the two.
Who runs it
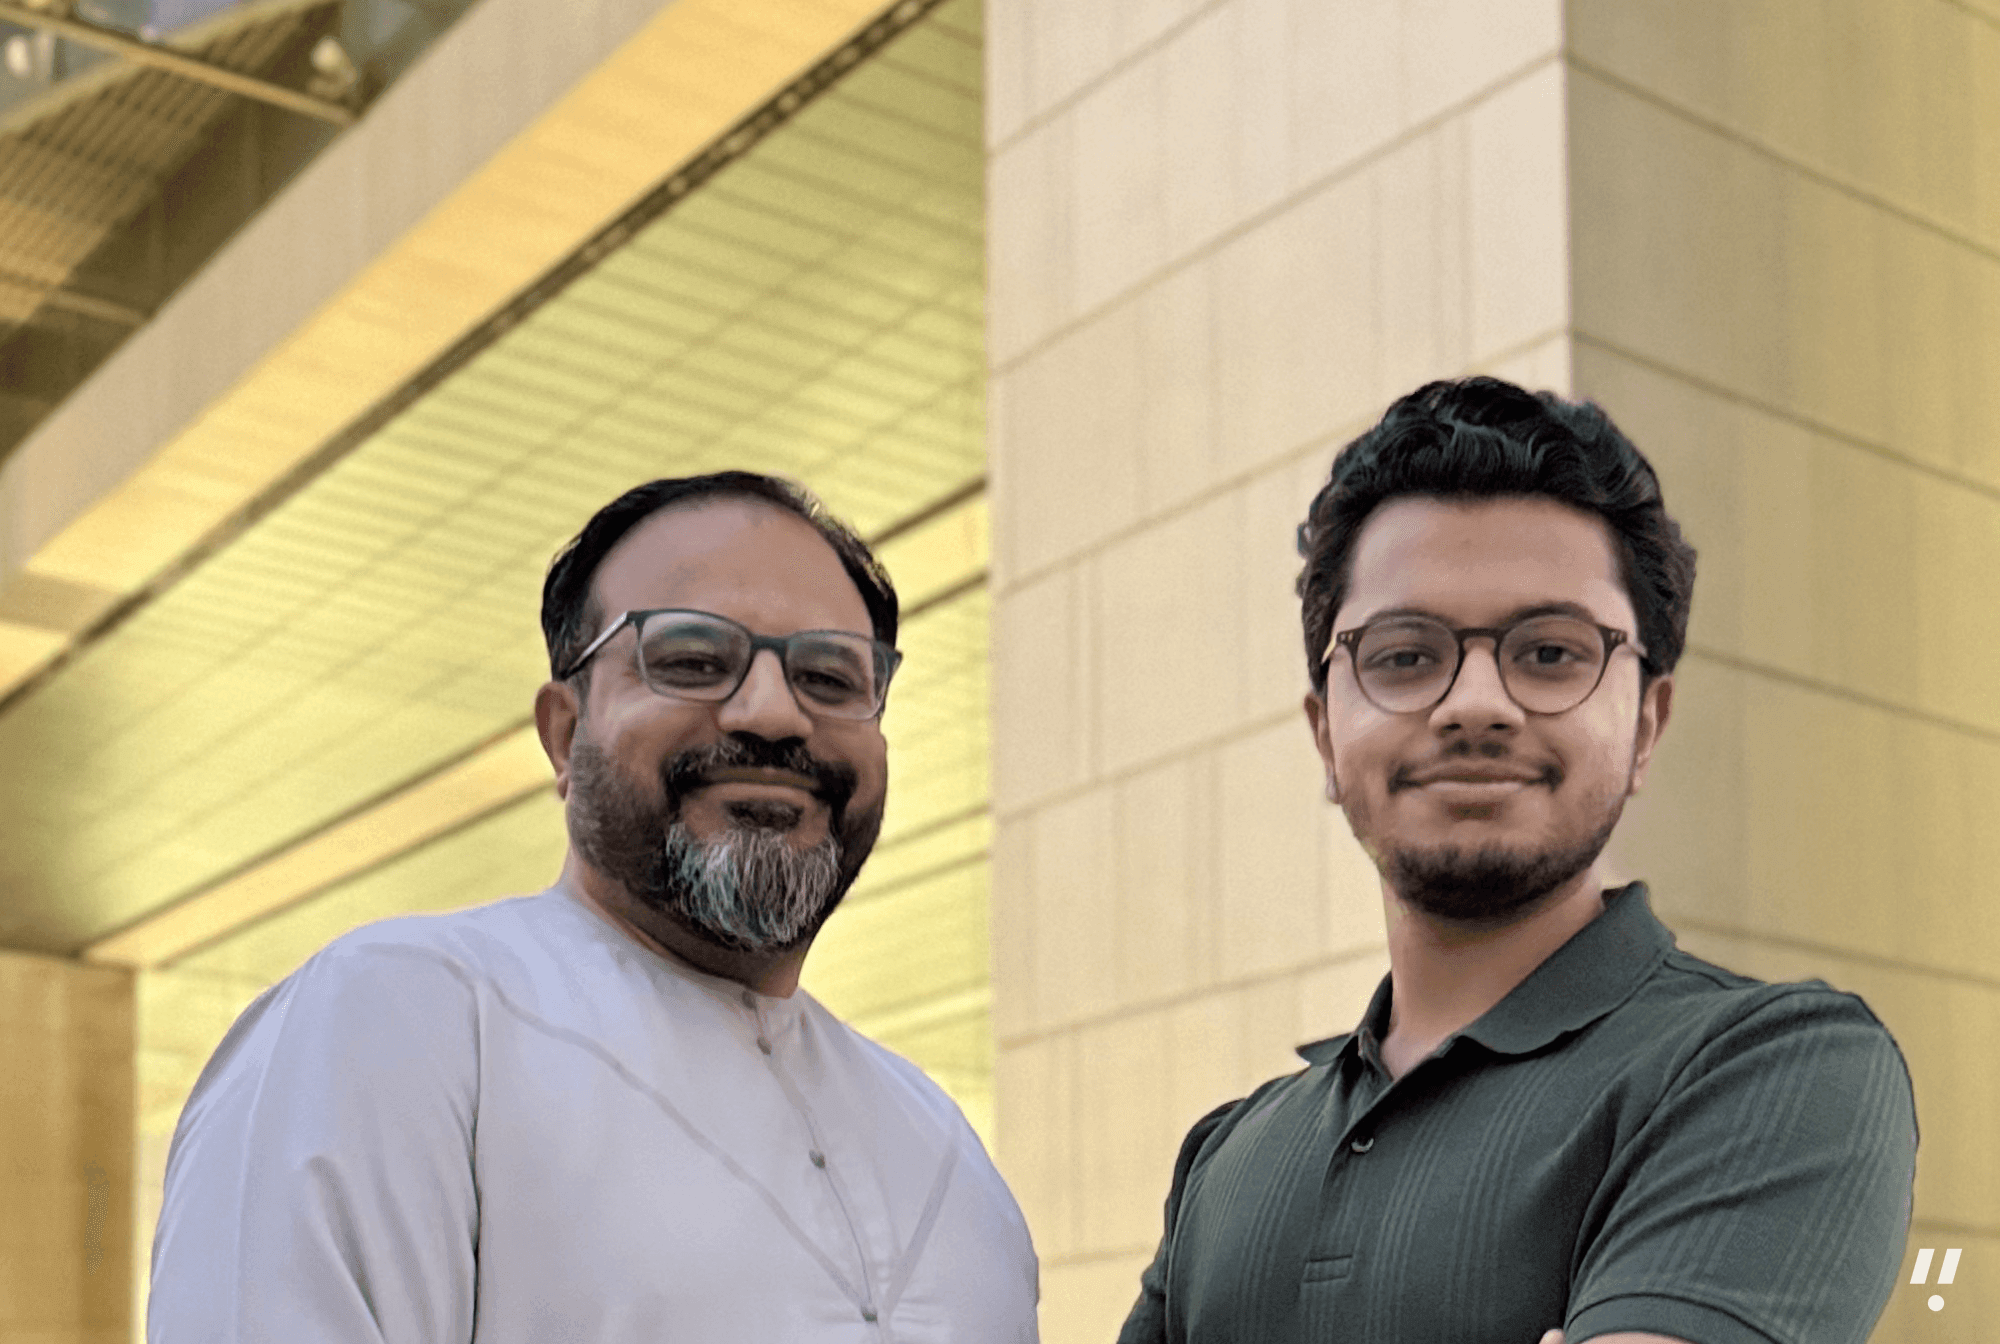
Muhammad Salman Anjum is CEO and Muhammad Ibrahim is COO. Both are listed as founders. The company was named a winner in a 2025 ranking of promising ventures from across the region.
Its claim to differentiation rests on the combination rather than any single part: an underwriting engine built for receivables, an on-chain record that prevents the same invoice being financed twice, and a front end that asks nothing of the borrower beyond a bank account. Whether that stack scales beyond its current book is the question the company now has to answer.

