Finance's next phase: connected data, Open Finance rails and AI agents
Products multiplied, but the work of joining them stayed with customers. Open Finance and AI promise to move that job onto the system itself.
Anecdoted Desk Anecdoted Desk covers rolling funding rounds and startup news across the UAE and MENA -- the wire for deals as they're announced. team@anecdoted.com
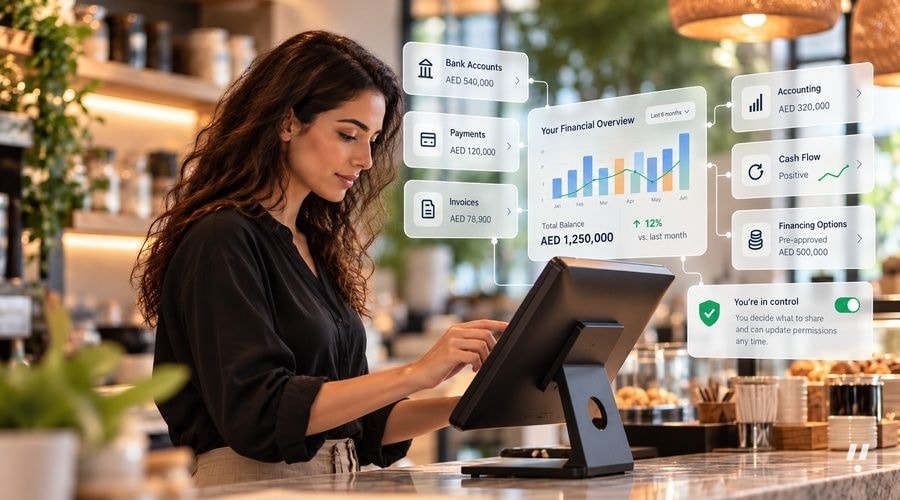
Technology platforms tend to follow one arc. Individual products get digitised first. Then they get linked to each other. At that point the edge stops being what any single product can do and becomes how well the whole system reasons together.
Smartphones travelled that path, folding hardware, software and services into a single experience. Cloud computing did the same, turning independent applications into linked systems that run at global scale. The discussion around artificial intelligence has already shifted from individual models to how many models, tools and workflows coordinate on harder problems.
Finance has arrived at the same point. Two decades of innovation delivered digital banks, payment platforms, accounting software and investing from a phone. Each solved a real problem. Yet every financial decision still rests on data held across separate institutions and platforms. Businesses reconcile payments between systems. Consumers assemble balances, commitments and goals by hand before deciding anything. The products improved quickly; the job of joining them stayed with the customer.
A business might take payments in one place, hold cash in another, invoice somewhere else and keep its books on a fourth platform. The owner becomes the integration layer. What the industry sees as a set of separate products feels like one financial life to the person running it.
That fragmentation has a cost. Hours spent reconciling records, shifting data between systems and deciding from a partial picture drag on productivity. At scale, scattered information also limits how efficiently capital moves.
Using 2019 data, the International Finance Corporation put the financing gap for micro, small and medium-sized enterprises across emerging and developing economies at $5.7 trillion. In the Middle East and North Africa, those gaps ranked among the largest relative to GDP, averaging close to 30%.
A company can post healthy revenue, reliable customers and predictable cash flow and still look opaque, because the signals sit in different systems. A lender sees only what it can reach. The business experiences the entire picture.
What connection changes
Picture a payment arriving from a customer. It lands in the bank account. The accounting platform updates on its own. Cash flow projections refresh. Working capital is recalculated. Financing options adjust to the newest position. The payment is the starting point, not the endpoint. What matters is that every linked product works from the same context and responds in step.
The consumer side works the same way. Guidance gets better when it reflects income, savings, investments, recurring commitments and long-term goals instead of isolated snapshots. AI makes those interactions conversational. Connected systems supply the context, letting products operate together rather than in isolation.
Open Finance is the groundwork. It lets customers share financial data securely across institutions, giving providers a joined-up view, within the limits of consent and whichever services are connected. It reaches further than Open Banking by covering a wider set of products and services, not just bank account data.
The UAE is building that layer at ecosystem scale. The Central Bank of the UAE introduced common infrastructure for secure data sharing and transaction initiation under its Open Finance framework, backed by an API Hub and a Trust Framework. The point is larger than any single product: shared rails that banks and fintechs can build on.
For the region, the timing is unusual. Much of MENA's digital financial infrastructure is going up now, while Open Finance and AI are becoming workable. Systems can be designed around today's consumers and businesses instead of yesterday's plumbing.
Brazil is the clearest reference point, because its central bank treated Open Finance as an ecosystem capability rather than a product line. Consented data gives institutions a richer read on financial behaviour, which supports faster and better-informed decisions. According to Banco Central do Brasil, credit operations originating from analysis of data shared through Open Finance reached R$31 billion between the start of implementation in 2021 and 30 June 2025, including R$5.4 billion in new credit extended by fintechs to 6 million customers. Building at that level takes common standards for consent, authentication, security and data sharing. Those standards are what make customers willing to let institutions and third parties work with their data.
Agents and authority
AI can reason over a financial context; connected systems give it the services it needs to act. That changes its role. Today a model can explain a transaction, summarise spending or answer a question about a product. With access to connected infrastructure and the right permissions, it can act on that understanding.
Take a business owner facing a cash flow gap. An agent could read incoming payments, expenses, invoices and balances, recognise an emerging shortfall, weigh the available options and set out the trade-offs. With permission, it could then act and track the result. For consumers, an agent could watch recurring commitments across linked accounts, spot an upcoming liquidity need, shift money between eligible accounts or start a payment under rules the customer has set.
How much authority to hand over is the harder question. An agent can analyse, recommend and prepare. The customer decides what it may do, inside defined permissions and controls. The more consequential the action, the more transparency, authentication and human oversight it demands.
Liability when an agent errs is unsettled. So is consent that runs continuously rather than per transaction, and the ceiling on what a customer should delegate. Those answers will decide how quickly agents stop being an interesting technology and start being trusted with money.

