Jingle Pay's Amir Fardghassemi Builds Licensed Rails Toward $10 Billion
The Dubai-based founder turned a remittance comparison app into payment infrastructure that moves fiat and stablecoins across 20-plus corridors.
Karim El-Sayed Karim El-Sayed covers company news, policy and regulation across the UAE and wider MENA for Anecdoted, with a focus on how new rules and licences reshape how startups operate. karim@anecdoted.com
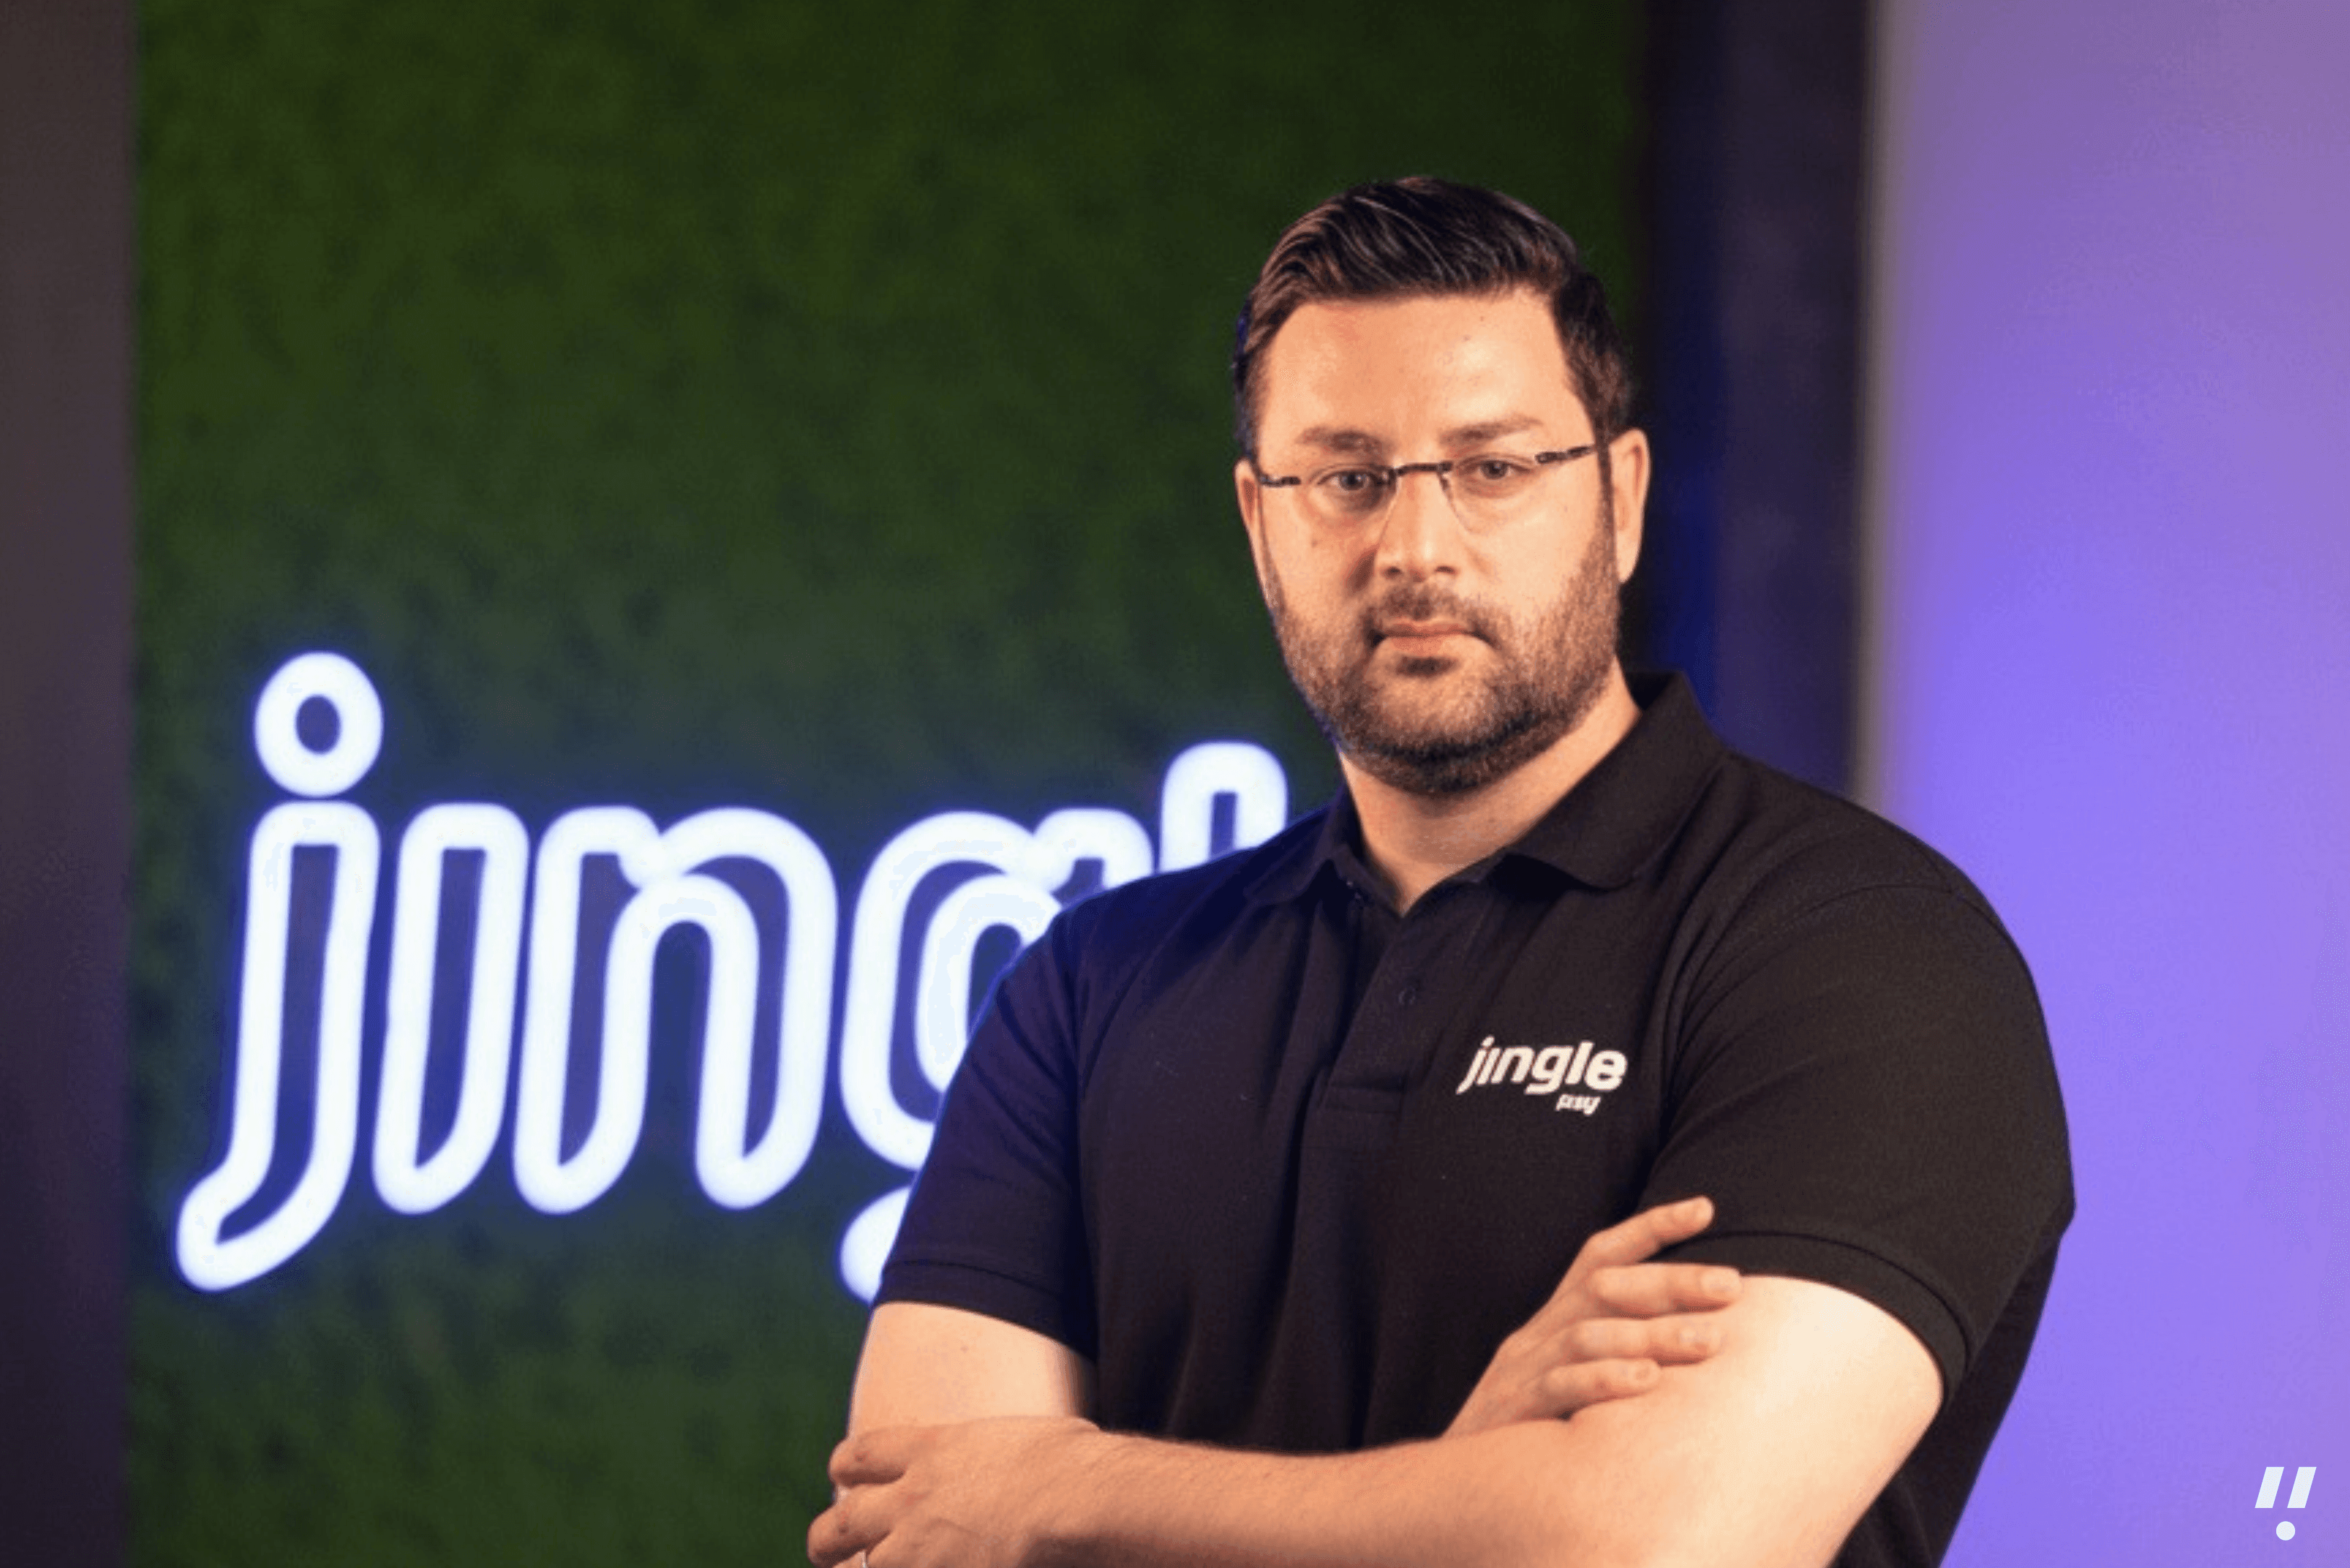
Amir Fardghassemi spent more than 15 years in finance, running a hedge fund before building and selling companies. One mismatch kept pulling at him: a message travels from Dubai to Lahore in a second, while money takes days, costs a great deal and often breaks somewhere in the middle.
Jingle Pay is his answer. It began as a consumer app for UAE expatriates sending money home, built around an idea the company says had not been tried before: a remittance marketplace where a sender sees every provider's rate side by side and picks one. Jingle Pay has since moved more than US$4.5 billion for senders worldwide, reaching 150-plus countries and 99-plus currencies, and has saved them over US$67 million.
An app that became the plumbing
Running that marketplace changed the company's direction. To display each provider's price and route every transfer to the best one, Jingle Pay had to connect to all of them, hold liquidity across all of them, and screen and settle each transaction itself. That is the plumbing of the industry. The providers being compared began asking to use it instead.
The consumer app remains live in the UAE, Pakistan and Bahrain, with Canada next. The infrastructure underneath now runs more than 20 corridors across APAC, MENAP and Latin America, moves money between Web2 and Web3, and draws most of its volume from other companies. Fardghassemi describes it as an AI-first operating system for global money movement.
Why Pakistan came first
Pakistan is one of the largest remittance markets in the world, and Jingle Pay became the leading player sending money into it. Doing that at volume meant solving liquidity, settlement, compliance, local banking rules and the many rails funds can arrive on. Each new corridor repeats those problems in a different shape; a corridor into the Philippines does not behave like one into India. Rather than rebuild the plumbing each time, the company converted what it learned in Pakistan into a platform that can be pointed at any market.
What the platform handles
It sits between a company that wants to move money and the messy reality of how money moves. A bank, a money transfer operator or a wallet integrates once. Jingle Pay then handles currencies, liquidity, screening and payout, whether the destination is a bank account in Karachi, a wallet in Manila or a cash counter in Casablanca. AI takes over the tasks humans did slowly: screening names, pricing corridors, forecasting where liquidity is needed and flagging transactions that look wrong. Adding a corridor becomes a configuration job rather than a build, which is how the network reached 20-plus corridors.
Money did not globalise the way information did, Fardghassemi argues. It still crosses borders much as it did in the 1970s, he says, slowly, expensively and through a chain of intermediaries who each take a cut and none of whom coordinate. The aim is not a faster version of that chain but a replacement for it.
Fiat on one side, stablecoins on the other
The system also treats different forms of money as interchangeable. A partner can send dollars and have pesos arrive in a wallet, or send a stablecoin and have rupees land in a bank account, or fund a corridor with a stablecoin that clears on a Sunday when banks are shut and pay out in cash on Monday morning. The sender never learns which rail was used. Fardghassemi does not cast stablecoins as a substitute for banking. He calls them another rail that happens to be fast and always on, and stresses interoperability between fiat and digital assets and between bank accounts, wallets and cash pickup.
Partners and permissions
MoneyGram made a strategic investment in 2022. Mastercard followed with a partnership that added physical and virtual cards to the product. Western Union and BOTIM, the UAE's largest messaging app, both run flows through Jingle Pay's infrastructure.
Licensing underpins the rest. Jingle Pay is regulated by the Dubai Financial Services Authority, with permissions covering money transmission, issuing payment instruments, issuing stored value and arranging money services. It is licensed in Canada, holds regulatory approvals in Bahrain and Pakistan, and holds virtual-asset permissions that allow it to link fiat and digital-asset flows inside a regulated framework. Four jurisdictions, four regulators. Fardghassemi's argument is that technology can be copied within a quarter, while permissions cannot be, and that few of the companies positioning themselves between banks and stablecoins are licensed on both sides.
From US$5 billion to US$10 billion
Jingle Pay processes roughly US$5 billion a year in payment volume from its Dubai base. At that scale, liquidity, settlement and compliance stop being support functions and become the business. The next target is US$10 billion, and the route is already moving: a treasury-as-a-service product recently went live, B2C and B2B payments are rolling out across the expanded corridor map, and more corridors are being switched on, each adding endpoints without adding a system to run. Fardghassemi calls the current figure a receipt, not a trophy. His test is whether a dollar, a dirham or a stablecoin can enter the system anywhere and come out as cash, a wallet balance or a bank credit anywhere else without anyone having to think about how. Across every corridor, he says, that is not true yet.

